Underwrite the Roof
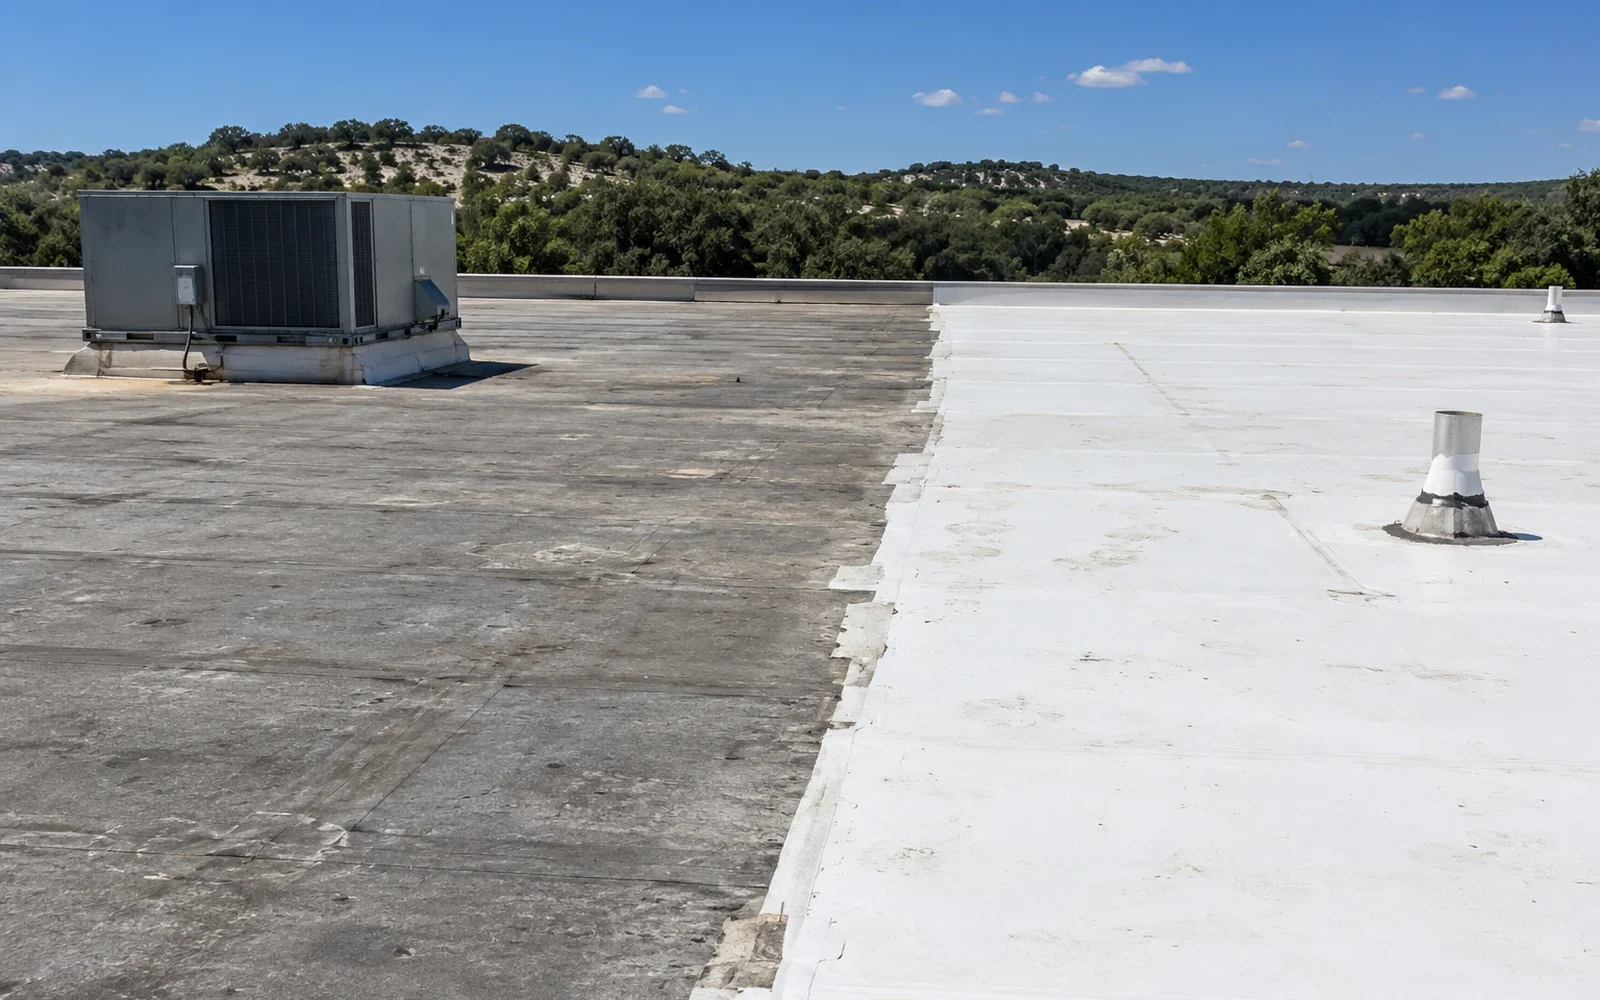
Underwriting a roof means putting a number on its remaining service and the cost of the next large event. We start with the membrane type, the layer count, the insulation condition and the history of repairs. A moisture scan finds wet insulation that a visual walk cannot, and core samples confirm the layers and the deck. The result is a range of years and a range of dollars, with the assumptions shown.
That range goes into the model as a reserve, a near-term capital item or a credit in a purchase negotiation. Our due diligence roof surveys are scoped to fit a contract inspection period, with access needs listed in the first message so a seller can clear them. Where access is limited, the report states what could not be checked, so the buyer prices the gap and does not ignore it.
The underwriting file also records what was not found. A roof with dry cores in three locations and no moisture anomaly on the scan earns a different range than a roof where access limited the work to a visual walk. Showing that difference lets a buyer, a lender and an asset manager weigh the same page and reach the same conclusion about how firm the numbers are.
A seller's roof file is worth more when it is dated. Photographs with dates, scan maps and repair invoices let a buyer's reviewer confirm the story quickly, and where the file is thin we say so, which lets the buyer price the uncertainty instead of discovering it after closing.